All Categories
Featured
Why Global Risk Requires Specialized Coverage
Policy Planning for Disabled Families

How to Secure Impaired Risk Insurance
Expert Underwriting for Impaired Risk
Table of Contents

Life insurance can provide essential monetary defense for enjoyed ones, however those with preexisting conditions often have a harder time getting a life insurance policy. Still, numerous medical conditions, including diabetes, do not immediately disqualify an individual for insurance coverage. For the most part, individuals with diabetes can still get life insurance coverage; they might need to pay more than an individual without a pre-existing condition.
In this short article, we'll assist describe: Insurance coverage service providers base premiums on the applicant's anticipated durability. Preexisting medical conditions can shorten life span, which is why life insurance coverage for some diabetics tends to be costlier than it is for people with no pre-existing conditions. Even when blood glucose is well controlled, the disease can possibly trigger issues, so it is a risk factor.
These include, however aren't restricted to: ObesityHeart diseaseHigh high blood pressure (high blood pressure)HypertensionStrokeIssues with eyes, teeth, and other organsKidney disease or failureNeuropathyLimb amputationHowever, not all diabetics are the same. Life insurance coverage business rate applicant threat based upon a number of elements, including case history, family medical history, current health, age, and lifestyle (such as tobacco use).
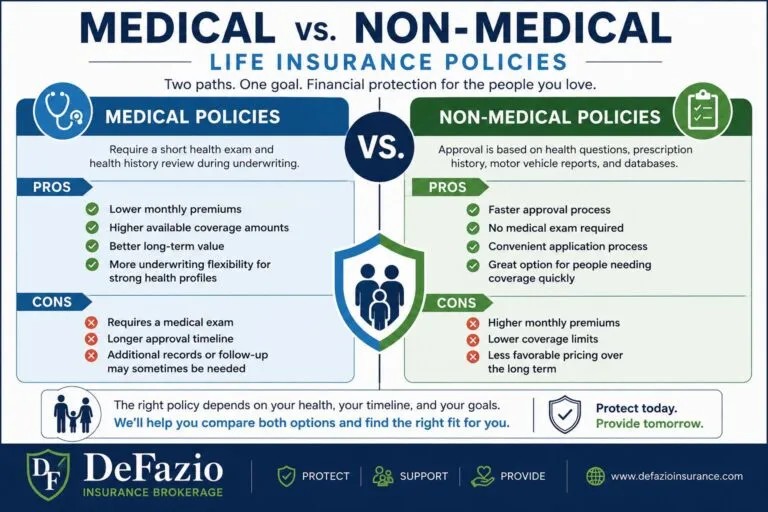
Candidates with well-managed diabetes and no issues might qualify for more beneficial policy terms. The life insurance coverage business will normally have you finish a medical underwriting process to identify your danger to guarantee. This can consist of a questionnaire that inquires about your diabetes, in addition to the basic medical questions on the life insurance application.
Insulin therapy, which is often required for Type 1 diabetes and often for Type 2 diabetes, might affect life insurance premiums. The insurance business may likewise need medical records to confirm your health history. In addition, you will often need to finish a physical examination (specifically if you're making an application for a high coverage quantity), and the life insurance business might likewise need a microalbumin test, which can help identify early signs of kidney damage.
How Cancer Survivors Should Secure Coverage
complete underwriting policies" below.) As part of the underwriting process, the life insurance company will likewise ask about the type of diabetes you have: Type 1 Diabetes, Type 2 Diabetes, or Gestational Diabetes. Individuals with each type of diabetes can still get life insurance coverage, however depending upon the base diagnosis, the application process may be more cumbersome, and the coverage offerings more minimal.
Life Insurance for Cancer SurvivorsWhen it takes place later in life, that suggests it has actually affected your body and health for a much shorter length of time. Type 1 diabetes is typically detected in kids or teens, making it a greater danger, and for that factor, it is usually associated with higher premiums. Type 2 diabetes is typically diagnosed at a later age than Type 1, so it has less time to impact the body.
If that is the case, and you have actually discovered how to keep it under control with diet plan and exercise, you will likely qualify for the most inexpensive rates (in relation to others with diabetes). Nevertheless, even with Type 2 diabetes, people with diabetes-related complications and those who are insulin-dependent will find their life insurance coverage choices more limited and their premium costs greater due to higher threat.
In a lot of instances, gestational diabetes disappears after delivering, however not constantly. In any case, pregnant women with gestational diabetes may wish to wait several months after delivering before looking for life insurance coverage. Presuming the diabetes disappears, it will then be much easier and less costly to get a life insurance policy.
Many term policies can transform to long-term life insurance coverage before the term expires without requiring additional medical underwriting. If offered, conversion can be an option to think about for people who purchased a term life insurance policy before they were identified with diabetes and wish to extend their protection. Long-term policies, such as whole life insurance coverage or universal life insurance, are generally more pricey, however they are designed to cover you for life.
Comparing Diabetic Life Insurance Policies in 2026
2,3 It may be best to buy as much life insurance coverage as you'll require (and can pay for) as soon as possible, instead of wait to include more later on. This is because life insurance coverage ends up being more expensive the older you get, and an underlying condition like diabetes will usually raise the expense even more.

Table of Contents
Latest Posts

Why Global Risk Requires Specialized Coverage
How to Qualify for Coverage For Chronic Kidney Disease (Ckd) And Dialysis Patients with Diabetes

Policy Planning for Disabled Families
Latest Posts
Why Global Risk Requires Specialized Coverage
How to Qualify for Coverage For Chronic Kidney Disease (Ckd) And Dialysis Patients with Diabetes
Policy Planning for Disabled Families